Can You Afford a House and a Wedding in the Same Year?
The arithmetic most couples avoid until it's too late to change the answer.
If you're trying to save for a house and a wedding at the same time, you've probably done the maths for each one separately, felt reasonably good about both, and never put the two monthly numbers side by side. That last step is where the plan usually breaks. Two goals that each look affordable in isolation can be impossible together, and the gap doesn't announce itself. It shows up eighteen months later as a raided deposit or a wedding on a credit card.
This guide walks the actual numbers: what each goal costs per month, why they collide, and the three honest ways out. If you haven't established your starting point yet, begin with calculating your net worth, because you can't price a deposit against savings you haven't counted.
1. What each goal actually costs per month
Start by pricing each goal on its own timeline. For goals under about three years, cash-equivalent returns are small enough that simple division is close enough to plan with.
- Wedding: $35,000, 18 months away. Money this close to being spent belongs in cash or high-yield savings, not equities. Monthly cost: $35,000 divided by 18, about $1,945.
- House deposit: $80,000, 4 years away. Long enough for a conservative mix to contribute, not long enough for equity risk. Monthly cost, growing at a conservative 4% a year: about $1,540.
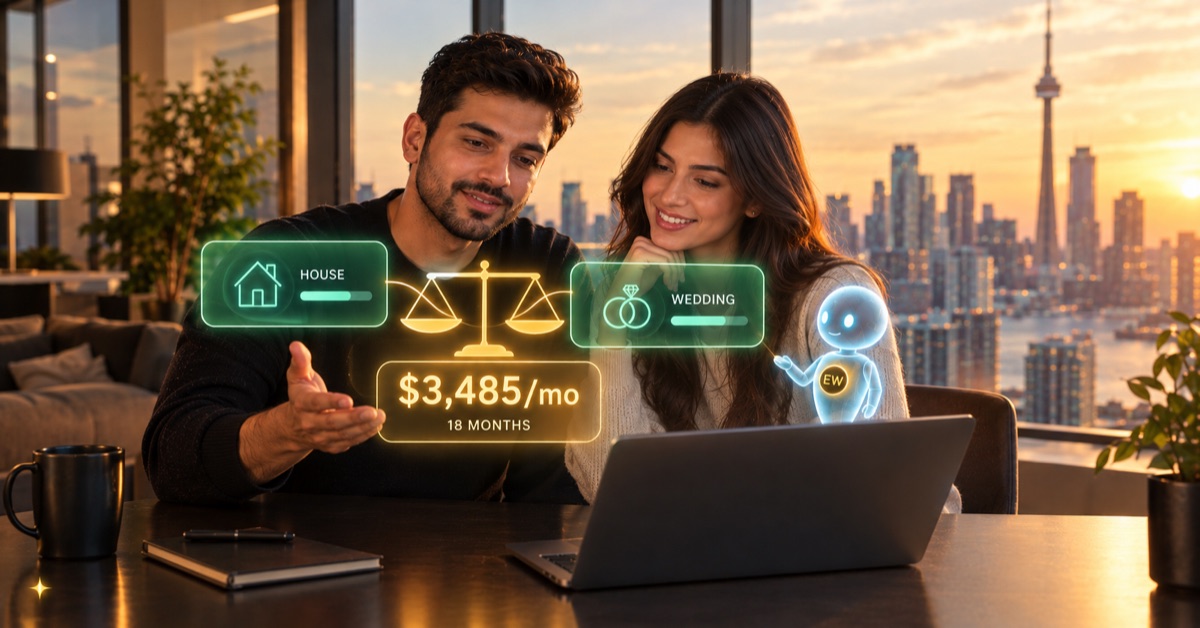
Separately, each is a normal-sounding number. Together they're about $3,485 per month. On a combined take-home of $8,000, that's about 44% of income going to two goals, before rent, food, retirement, or anything else.
In Canada, the house deposit part of this math has an extra layer: which account holds it. An FHSA, a TFSA, and an RRSP withdrawn under the Home Buyers' Plan each come with different tax treatment and different repayment rules. See TFSA vs RRSP vs FHSA for a house down payment for the account-by-account breakdown. And whatever you do, keep the wedding money out of the FHSA: see can you use an FHSA for a wedding for why a non-qualifying withdrawal is fully taxable. If you are both saving in FHSAs for the same home, see FHSA for couples.
✓ What to do this week
2. Why the collision is worse than it looks
The short goal crowds out the long one
The wedding is closer, louder, and has a fixed date with other people's expectations attached. When money gets tight, the deposit gets cut, quietly, a month at a time. The wedding almost always wins, not because it's more important, but because it's more urgent.
Short horizons can't use growth to help
An 18-month goal has to be funded almost entirely out of contributions. A ten-year goal can let compounding do a third of the work. Two short goals stacked together give you maximum monthly demand and minimum help from returns.
The overlap period is where it actually breaks
The full $3,485 isn't required for four years. It's required for the eighteen months where both goals are live. After the wedding, the deposit continues alone at $1,540, which is comfortably affordable. You don't need to fund both goals for four years; you need to survive eighteen months.
3. The three honest options
Give one goal more time
Push the deposit from four years to six. Monthly cost drops from $1,540 to about $985, and the combined peak falls to about $2,930, or about 37% of income instead of 44%. You haven't given up the house; you've bought breathing room with time you weren't using.
Right-size a target
A $35,000 wedding at $28,000 releases $390 a month in the exact window where money is tightest. A 20% trim to the goal causing the squeeze often costs less in lived experience than eighteen months of financial strain.
Stagger deliberately rather than by accident
Fund the wedding hard for eighteen months while contributing a token amount to the deposit, then redirect the entire $1,945 the month after the wedding. This is usually what happens anyway. The difference is choosing it, with a date attached, instead of drifting into it and feeling behind.
4. The staggered plan, in numbers
- Months 1 to 18: $1,945 to the wedding, $300 to the deposit. Total $2,245, or about 28% of income, sustainable alongside normal life.
- Wedding funded on schedule. Deposit balance at month 18: about $5,550, growing at 4% a year.
- Months 19 to 48: the full $2,245 redirects to the deposit. Thirty months adds about $67,350 in deposits, plus growth.
- Deposit at month 48: about $76,750 against an $80,000 target.
Short by about $3,250, which you now know four years early, when it's still fixable by extending about two months or trimming the target, rather than discovering it at the mortgage application. That's the entire value of putting both numbers on one page.
Frequently asked questions
Can we invest the wedding money to make it grow faster?
With an 18-month horizon, no. A drawdown in the final six months would leave you short with no time to recover, and the expected gain is small relative to the risk. Money you'll spend within about three years belongs in cash equivalents.
What if both sets of parents are contributing?
Treat committed contributions as a reduction to the target, not as income. A confirmed $10,000 lowers a $35,000 target to $25,000 and the monthly cost to about $1,390. Don't plan around money that's been mentioned but not committed.
Put both goals on one page. The EnvisionWorth planner prices each goal on its own timeline, totals them against your income, and shows the overlap window before you commit to either. It runs in your browser, and no account is needed to see your number.
See your goals on one page
The EnvisionWorth calculator prices each of your financial goals on its own timeline and adds them into one monthly Dream Number, then shows where two goals compete for the same dollar and what a what-if change (delaying, resizing, or reordering a goal) does to the rest. It runs in your browser, and no account is needed to see your number.
Try the free calculator⚠️ Disclaimer
This content is for educational purposes only and does not constitute financial, investment, tax, or legal advice. EnvisionWorth provides technology and educational resources; we do not provide personalized financial advice. Past performance does not guarantee future results. All investment decisions should be made in consultation with qualified financial professionals.
Avish Shah
Founder, EnvisionWorth Financial Intelligence
EnvisionWorth helps you plan all your financial goals together, give every dollar a job toward a goal, and see what needs attention.
Continue Your Journey
Explore more insights to enhance your financial intelligence
TFSA vs RRSP vs FHSA for a House Down Payment: Which Should Hold Your Money?
FHSA, RRSP Home Buyers' Plan, or TFSA: the CRA rules for each, the order that gets first-time buyers to a down payment fastest, and a worked Canadian example that keeps retirement funded too.
Can You Use an FHSA for a Wedding? The Real Tax Cost If You Try
An FHSA withdrawal for anything but a qualifying home is fully taxable, and the room does not come back. The CRA rules, the real cost of getting it wrong, and where wedding money should sit while the house goal keeps building.
How to Prioritize Financial Goals Without Robbing One to Pay Another
Ranking goals is the easy part. This is what to do with the goals that lose: sequencing versus splitting, the real cost of delay by goal type, and when partial funding wins.