How to Prioritize Financial Goals Without Robbing One to Pay Another
Sequencing, splitting, and the real cost of delay. A framework for when you can't fund everything.
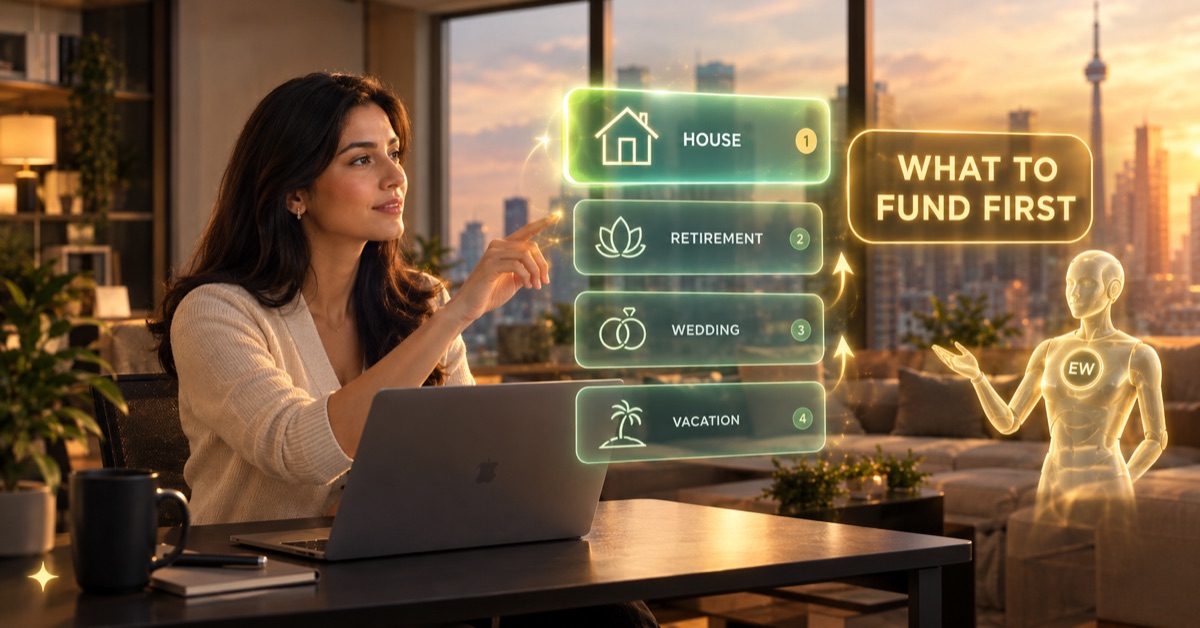
The short answer: put two kinds of goals first. Goals with a fixed date you cannot move, like a wedding or a tuition bill, and goals that quietly cost you more the longer you wait, like retirement. For everything else, you have two honest choices. Finish one goal at a time so it is done fast, or put a little toward several at once so none of them stalls. The rest of this guide shows you how to pick between those two, and what each choice really costs.
Everyone tells you to prioritize your financial goals. Almost nobody tells you what to do with the goals that lose. That's the actual problem: prioritisation advice usually stops at "rank them", as if ranking were the hard part, when the hard part is deciding whether the goal ranked third gets 20% funding, 0% funding, or a later start date, and what each of those choices costs.
This guide gives you a way to make that call with numbers instead of guilt. It assumes you already have goals with real prices attached; if not, start with financial goal planning and come back.
1. Why "just save more" is not a plan
The default response to competing goals is to try harder: cut spending, pick up extra work, squeeze the budget. Sometimes that works. Usually it fails structurally: the shortfall on overlapping goals is often 20-40% of take-home income, and no realistic amount of discretionary trimming closes a gap that size.
Worse, "save more" has no stopping condition. It never tells you whether you're on track, so you feel behind permanently regardless of how well you're doing. A plan that says "contribute $1,240 a month and you'll arrive in March 2029" can be satisfied. "Save more" cannot.
✓ What to do this week
2. The order that works for most people
When you genuinely cannot fund everything, this default order protects you from the most expensive mistakes first. Treat it as a starting point and adjust it to your life, but start here.
- A one-month cash buffer. Before anything else, so a surprise bill does not put you back into debt and undo the rest.
- Any employer match. It is an immediate, guaranteed return you will not find anywhere else. Contribute enough to get the full match, then stop for now.
- High-interest debt. Anything above roughly 7 to 8 percent costs you more than most goals will earn, so clearing it is the better use of the money.
- Goals with a fixed date you cannot move. A wedding, a tuition bill, a lease ending. These get funded or resized, and resizing should happen early while it is still a calm decision.
- Long-horizon goals like retirement. Boring, invisible, and the most expensive to delay, because you lose the compounding as well as the contributions.
- Everything flexible. Travel, a bigger car, a renovation. These are your release valve, because moving them costs the least.
Notice that retirement sits below the deadline goals but above the flexible ones. That is deliberate. A delayed holiday is a changed plan you barely feel. A delayed retirement quietly costs you the most of all, which is exactly why it rarely feels urgent.
3. Sequencing versus splitting
Splitting: fund everything partially
Divide available money across all goals, each at reduced contribution. Every goal moves; every goal arrives late. This feels fair and keeps momentum visible on all fronts, which matters when goals are shared between partners with different priorities. The cost is that no goal gets the concentrated funding that would let it finish, and short-horizon goals suffer disproportionately.
Sequencing: fund one hard, then the next
Direct nearly everything at one goal until complete, then redirect the entire flow. Goals finish dramatically faster in sequence, and finishing matters, because a completed goal frees its whole contribution permanently. The cost is that goals at the back sit still for years, which is hard to sustain when one belongs to a partner who didn't rank it third.
When each one wins
- Sequence when goals have flexible dates, when one is close to completion, or when they belong to the same person and purpose.
- Split when goals have hard external deadlines, when they belong to different people, or when one is an emergency fund, which is a prerequisite, not a competitor.
4. What delay actually costs, by goal type
Long-horizon goals: delay is expensive but invisible
Postponing retirement contributions by three years in your thirties doesn't cost three years of contributions. It costs those contributions plus every year of compounding they'd have earned, which on a thirty-year horizon can be two to three times the amount deferred. The most expensive delay available, and the one that generates the least urgency.
Short-horizon goals: delay is cheap but disruptive
Pushing a vacation fund out six months costs almost nothing financially, because there was little compounding to forgo. It costs a changed plan and a conversation. Short goals are the cheapest to move, which makes them the correct release valve far more often than people assume.
Deadline goals: delay is not available
A wedding date, a tuition bill, a lease ending. These can't move without moving something in the real world, so they must be funded or resized. Resizing should happen early. A target trimmed 24 months out is a planning decision; the same trim 3 months out is a crisis.
5. When partial funding beats full funding
- Employer matching. Contributing to the match and no further is partial funding with an immediate guaranteed return. Take it before anything else, including debt in most cases.
- Goals with variable targets. A "renovate the kitchen" goal at 60% funding is a smaller renovation, not a failed one. Goals that scale should be partially funded rather than deferred.
- Keeping a goal psychologically alive. A token $100 a month to a partner's otherwise zero-funded goal costs little and prevents the resentment that derails the whole plan. Not financially optimal, and frequently the right call.
The case against partial funding is fixed-threshold goals: a house deposit at 70% isn't 70% of a house, it's a rental. Goals with a cliff should be sequenced, not split. In Canada, which registered account a house deposit sits in (FHSA, TFSA, or an RRSP Home Buyers' Plan withdrawal) is its own sequencing decision. See TFSA vs RRSP vs FHSA for a house down payment. For retirement money, see TFSA vs RRSP: which to fill first.
6. Two ideas that make this easier
The Dream Number
Most planning hands you a retirement number: one large figure that quietly assumes everything you want before retirement does not exist. Your Dream Number is the opposite. It is the single monthly amount that funds all your goals at once, the house and the wedding and retirement together, so you can see whether they fit your income before you are forced to choose between them. Once you know that number, the rest of your money is yours to spend on the present without guilt.
Purpose per asset
The money you already own can do this work too. Purpose per asset means giving every dollar a job: this account is the house, these shares are retirement, this cash is the wedding. Once each asset has a purpose, you stop accidentally spending one goal's money on another, and you can see the exact point a goal is fully funded. That single habit prevents the most common and most painful planning mistake there is. If you already log your balances each month, you can start today: add a goal column to your net worth tracker and write each account's job next to it.
This is the whole job EnvisionWorth does for you. It puts your goals, your income, and the assets you already own into one plan, then tells you honestly where each goal stands: on track, ahead, or behind, the year it will land, and the exact monthly it takes from here, compared with what you are contributing now. It does not stop at closing gaps. When a goal is ahead, it shows you how to finish it early or free that money for the present without pushing the date back. When one is behind, it often finds spare money from a goal that is ahead and brings several behind goals back on track with no new money from you. It shows what putting unassigned cash to work could do for a goal, and flags when an asset does not suit the goal it is funding.
Every figure is arithmetic on your own accounts, not generic advice. Each suggestion carries its reason and the assumptions behind it, and it opens the real screen with the change already loaded so you can test it before you commit. You stay in control. It recommends. Nothing moves until you decide. You can see where your own goals stand in the free planner.
Frequently asked questions
Should I pay off debt or fund goals first?
Compare the interest rate to the expected return of the goal's allocation. Debt above roughly 7-8% almost always wins. Below about 4%, funding goals usually wins. Between those it's close enough that the psychological benefit of clearing the debt is a legitimate tiebreaker.
How often should I re-rank my goals?
Annually, or when something material changes: income, a new goal, a completed one. Re-ranking more often turns into reacting to whichever goal feels loudest this month, which is the failure the framework exists to prevent.
What if my partner and I rank goals differently?
Resolve it by cost, not by argument. Price both orderings and compare arrival dates for each goal under each. Disagreements shrink once the real difference in outcomes is visible, and the two orderings often differ by only a few months.
Which financial goal should I fund first?
For most situations, fund in this order: a one-month cash buffer, any employer match, high-interest debt above roughly 7 to 8 percent, goals with a fixed date you cannot move, long-horizon goals like retirement, then anything flexible. Retirement sits above the flexible goals on purpose, because delaying it costs the most in lost compounding.
Can I save for multiple financial goals at once?
Yes, and most people should. Splitting your money across several goals keeps them all moving, which matters when goals have hard deadlines or belong to different people. The trade-off is that no single goal finishes as fast. Fund one goal hard instead when it shares a purpose with the others or sits close to the finish line.
Related reading: a house and a wedding in the same year and why the spreadsheet method quietly fails.
See your goals on one page
The EnvisionWorth calculator prices each of your financial goals on its own timeline and adds them into one monthly Dream Number, then shows where two goals compete for the same dollar and what a what-if change (delaying, resizing, or reordering a goal) does to the rest. It runs in your browser, and no account is needed to see your number.
Try the free calculator⚠️ Disclaimer
This content is for educational purposes only and does not constitute financial, investment, tax, or legal advice. EnvisionWorth provides technology and educational resources; we do not provide personalized financial advice. Past performance does not guarantee future results. All investment decisions should be made in consultation with qualified financial professionals.
Avish Shah
Founder, EnvisionWorth Financial Intelligence
EnvisionWorth helps you plan all your financial goals together, give every dollar a job toward a goal, and see what needs attention.
Continue Your Journey
Explore more insights to enhance your financial intelligence
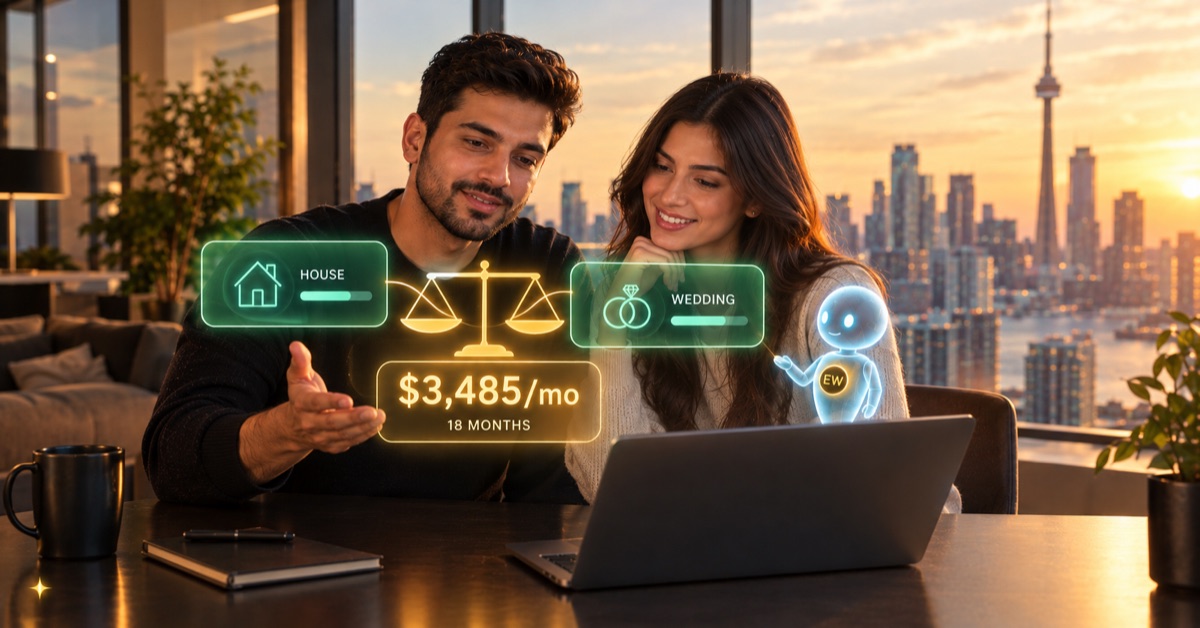
Can You Afford a House and a Wedding in the Same Year?
Two goals that look affordable separately can be impossible together. The month-by-month numbers on funding a house deposit and a wedding at once, and the three ways out.
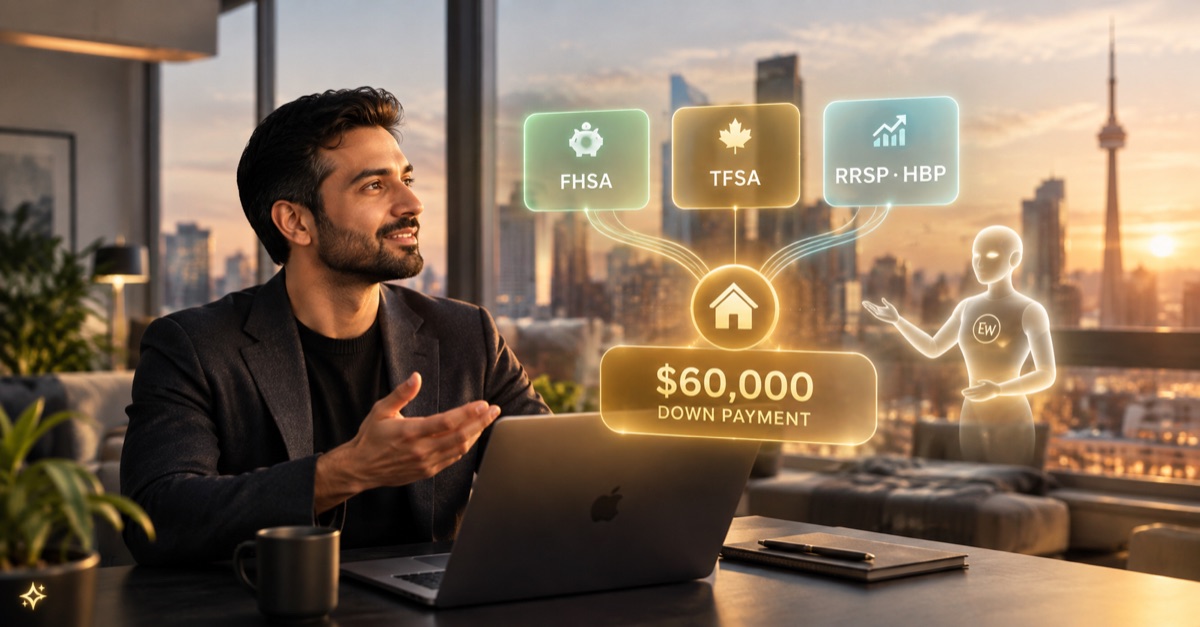
TFSA vs RRSP vs FHSA for a House Down Payment: Which Should Hold Your Money?
FHSA, RRSP Home Buyers' Plan, or TFSA: the CRA rules for each, the order that gets first-time buyers to a down payment fastest, and a worked Canadian example that keeps retirement funded too.
Can You Use an FHSA for a Wedding? The Real Tax Cost If You Try
An FHSA withdrawal for anything but a qualifying home is fully taxable, and the room does not come back. The CRA rules, the real cost of getting it wrong, and where wedding money should sit while the house goal keeps building.
TFSA vs RRSP: Which Should You Fill First, and Why?
TFSA or RRSP first? It comes down to your tax rate now versus when the money comes out. An Ontario example, claiming the tax break later, and what changes it.