How to Calculate Net Worth (Without Feeling Overwhelmed): A Practical Step-by-Step Guide
From confusion to clarity: a simple monthly system anyone can run in 20 minutes.
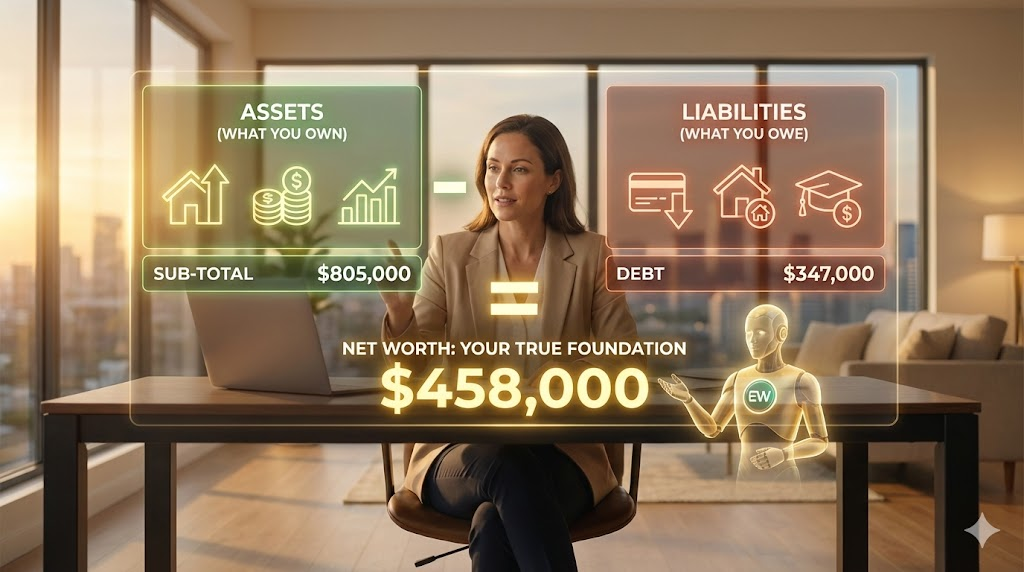
You're juggling rent or a mortgage, a car payment, maybe student loans or family bills, and trying to save and invest on top of it. It's easy to feel like you're working hard but unsure whether you're actually getting ahead. That's exactly the problem learning how to calculate net worth solves. Net worth is one honest number - everything you own minus everything you owe - that tells you where you really stand right now, and whether the past 12 months moved you forward or sideways.
This guide walks you through a practical 20-minute monthly process. Once you have your number, you can compare it to age-based benchmarks, set up a net worth tracker to automate the routine, and turn it into a real goal plan.
1. Why your net worth matters more than your income
Income tells you how fast money flows in. Net worth tells you how much you've kept. Two people with the same paycheck can be in very different places.
Consider Priya, who earns $140,000 a year. Between a $3,200 rent, a $620 car payment, and lifestyle spending, she ends most months at zero. Her net worth has barely moved in three years. Compare her to Marcus, who earns $72,000, lives in a lower-cost city, automatically routes $900 a month into a 401(k) and a Roth IRA, and overpays his student loans. Marcus's net worth grew by roughly $14,000 last year. Priya's grew by $1,500.
Neither person is "winning" or "losing" as a human being. But the number does not lie about the trajectory. That's why net worth is the foundation metric: it captures the result of every income, spending, debt, and investing decision you make.
✓ What to do this week
2. What to include (and what not to) in assets and liabilities
Your goal is an honest snapshot, not a flattering one. Here's what belongs on each side of the ledger.
Include as assets
- - Checking, savings, money market
- - Brokerage accounts at market value
- - 401(k), IRA, Roth IRA, RRSP, TFSA, pension cash value
- - HSA and 529 balances
- - Home equity (current market value)
- - Vehicles at private-party resale value
- - Vested business equity or RSUs (after-tax estimate)
Include as liabilities
- - Mortgage and HELOC balances
- - Auto loans
- - Student loans (federal and private)
- - Credit card balances (full statement balance)
- - Personal loans, family loans you owe
- - Tax owed but not yet paid
What to skip on a first pass: furniture, clothes, electronics, hobby gear, and most personal items. They depreciate fast and rarely sell for what you think. Leaving them out keeps your number conservative and useful. Also skip unvested stock options and unrealized inheritances - they're not yours yet.
✓ What to do this week
3. Your first net worth calculation in 20 minutes
Aim for "good enough" on the first pass. You can refine later. Here's the worksheet flow.
- Cash (3 minutes). Log into each bank app and write down today's balance.
- Investments (5 minutes). Pull the current value from each brokerage and retirement account. Don't worry about cost basis here - market value is what matters for net worth.
- Property (4 minutes). Estimate home value from a recent appraisal, recent neighborhood sales, or a Zestimate adjusted for your local market. Use private-party Kelley Blue Book for vehicles.
- Debts (5 minutes). Pull current balances on every loan and credit card. Use today's balance, not the original loan amount.
- Math (3 minutes). Sum assets. Sum liabilities. Subtract.
Worked example - the Patel household
Assets: $14,000 cash + $86,000 401(k) + $22,000 Roth IRA + $410,000 home + $18,000 car = $550,000.
Liabilities: $312,000 mortgage + $11,000 auto loan + $6,500 credit cards + $24,000 student loans = $353,500.
Net worth: $196,500.
✓ What to do this week
4. Common mistakes that make your number misleading
- Double counting. Listing a brokerage balance and the individual stocks inside it. Pick one level - account totals are simplest.
- Stale property values. Using a five-year-old home estimate or your purchase price. Refresh annually.
- Forgetting taxes on tax-deferred accounts. A $200,000 traditional 401(k) is not the same as $200,000 in cash. For a more realistic view, mentally haircut pre-tax retirement balances by 20-25%.
- Counting unvested equity. Stock options that vest in three years are not assets today.
- Ignoring small balances. Old 401(k)s from previous employers, an HSA you forgot, a checking account you barely use. Track them down once and you'll never miss them again.
- Pretending credit card debt isn't real. If it's not paid off this month, it's a liability.
✓ What to do this week
5. How to track net worth monthly without obsessing
The right cadence is monthly, not daily. Markets bounce around; your real progress shows up over months and years.
- Monthly (20 minutes). Refresh balances, log the new total, note one thing that changed (raise, big bill, market move).
- Quarterly (45 minutes). Look at the three-month trend. Is the savings rate where you want it? Are debts shrinking?
- Annually (90 minutes). Re-estimate property values. Reconcile retirement account holdings. Adjust your goal contributions.
If you connect accounts to a tracker, the monthly step shrinks to a five-minute review. See the net worth tracker setup guide for how to do this safely.
If this is your situation
Just starting out
Use a simple spreadsheet with one row per month. The act of typing the numbers is part of the learning. Don't even chart it yet - just stack 6 months.
Building momentum
Move to a tracker that pulls balances automatically. Set a recurring 20-minute calendar block on the first weekend of every month for review and journaling.
Optimizing
Track sub-metrics alongside net worth: savings rate, liquid net worth (excluding home equity), and net worth ex-retirement. These reveal flexibility, not just total wealth.
6. What to do after you know your number
A number on its own doesn't change anything. The point is the next decision. Here are three actions that almost always pay off.
- Pick a debt strategy. If you carry credit card or other high-interest debt, route every extra dollar there until it's gone. The "return" is the interest rate you stop paying - often 18-24%.
- Automate savings. Set a fixed dollar amount to move from checking to investing on payday. Automation beats willpower every month.
- Align portfolio to goals. If your money is sitting in cash but your goal is 15 years out, you're losing to inflation. If it's in stocks but you need it in 18 months, you're taking unnecessary risk. Match the money to the timeline using goal-based investing, and when goals compete for the same paycheck, decide the order with how to prioritize financial goals.
✓ What to do this week
7. The question your net worth number can't answer
Here is the limit of the number, and where most guides stop. Net worth tells you what you own today. It stays completely silent on the thing that actually keeps you up at night: is this money going to get me to the house, the wedding, and retirement, and is each one on track for its date. Two people can hit the exact same number and be in entirely different positions.
An illustrative example. Both households below have the same net worth.
| Both have $196,500 net worth (illustrative) | Alex | Sam |
|---|---|---|
| Money assigned to a goal | Every dollar has a job | One undifferentiated pile |
| House down payment | On track for 2028 | Unknown |
| Retirement | On track | Hopes so |
| Confidence when a bill hits | Knows what it delays | Guesses |
Same number, two different lives. The difference is not how much they own. It is whether each dollar knows which goal it is funding. That is the step after the snapshot, and it is a real skill of its own: when goals compete for the same paycheck, the order you fund them in matters. Start with how to prioritize financial goals without robbing one to pay another.
This is what EnvisionWorth is built to do. It reads your own accounts and gives you, for each goal, an estimate of whether it is on track, ahead, or behind, the projected year it lands, and the monthly it would take to get there. These are estimates based on your own numbers and assumptions, not guaranteed outcomes. When something needs attention it surfaces one move at a time with the reasoning behind it, for example putting idle cash to work or using spare money from a goal that is ahead to bring a behind goal on track. It recommends and shows its math. Nothing moves until you decide. You can price your own goals against your income in the free planner, no account needed.
Frequently asked questions
How do I calculate my net worth quickly?
Add up everything you own at today's value, then subtract everything you owe. A first pass takes about 20 minutes.
Should I include my home and car in net worth?
Yes. Use realistic current market value, not purchase price. Then list the loan balance as a liability so the equity portion shows up correctly.
How often should I calculate my net worth?
Monthly is the sweet spot. Pick the same date each month, spend 20 minutes, and let the trend tell the story over time.
What should I do with my net worth number once I have it?
Give every dollar a job. A net worth number tells you what you own, but not whether that money is on track for the things you are actually saving for. The next step is to assign each asset to a specific goal, a house, retirement, a wedding, and check whether each goal is on track for its date. Two people with the same net worth can be in very different positions depending on whether their money is committed to real goals or sitting undifferentiated.
See your goals on one page
The EnvisionWorth calculator prices each of your financial goals on its own timeline and adds them into one monthly Dream Number, then shows where two goals compete for the same dollar and what a what-if change (delaying, resizing, or reordering a goal) does to the rest. It runs in your browser, and no account is needed to see your number.
Try the free calculator⚠️ Disclaimer
This content is for educational purposes only and does not constitute financial, investment, tax, or legal advice. EnvisionWorth provides technology and educational resources; we do not provide personalized financial advice. Past performance does not guarantee future results. All investment decisions should be made in consultation with qualified financial professionals.
Avish Shah
Founder, EnvisionWorth Financial Intelligence
EnvisionWorth helps you plan all your financial goals together, give every dollar a job toward a goal, and see what needs attention.
Continue Your Journey
Explore more insights to enhance your financial intelligence
How to Prioritize Financial Goals Without Robbing One to Pay Another
Ranking goals is the easy part. This is what to do with the goals that lose: sequencing versus splitting, the real cost of delay by goal type, and when partial funding wins.
Net Worth by Age: Real Benchmarks, Real Context, and Your Personal Next Step
Median net worth by age for the US (Federal Reserve) and Canada (Statistics Canada), why averages mislead, and a scorecard to see where you stand.
Financial Goal Planning That Actually Works: From Wish List to Funded Plan
A goal-planning operating system for real people. Use the Now / Next / Later Goal Stack to put a real price on each goal, fund it monthly, and re-plan when life changes.
Net Worth Tracker: How to Choose One, Set It Up, and Act on What It Shows
Compare 4 ways to track net worth (spreadsheet, app, linked accounts, goal-based planner), copy a tracker layout, and tie each balance to the goal it serves.