Financial Goal Planning That Actually Works: From Wish List to Funded Plan
A goal-planning operating system for real people with real constraints.
Most financial goal planning falls apart not because the goals are wrong, but because they're never given a real price, a real timeline, and a real monthly funding source. A vague goal like "save for a house" is a wish. A funded goal like "$48,000 down payment by June 2028, $1,150 per paycheck into a high-yield savings account" is a plan. This guide shows you how to do that for every goal in your life, in a system simple enough that you'll actually use it.
Before you plan goals, know your starting point. See calculate your net worth. Once your plan is funded, pair it with a portfolio tracker for the long-horizon money and use an AI co-pilot to stress-test scenarios.
1. Why most financial goals fail (and how to avoid it)
- Vague target. "Save more" with no number, no date, no monthly contribution.
- No funding source. The goal lives in a spreadsheet but no money flows toward it from a paycheck.
- Wrong account. A 3-year goal sitting in equities; a 30-year goal sitting in cash.
- No review rhythm. The plan is built once, then ignored until the goal date arrives.
- Single-goal thinking. Pouring everything into retirement while ignoring a foreseeable car replacement.
✓ What to do this week
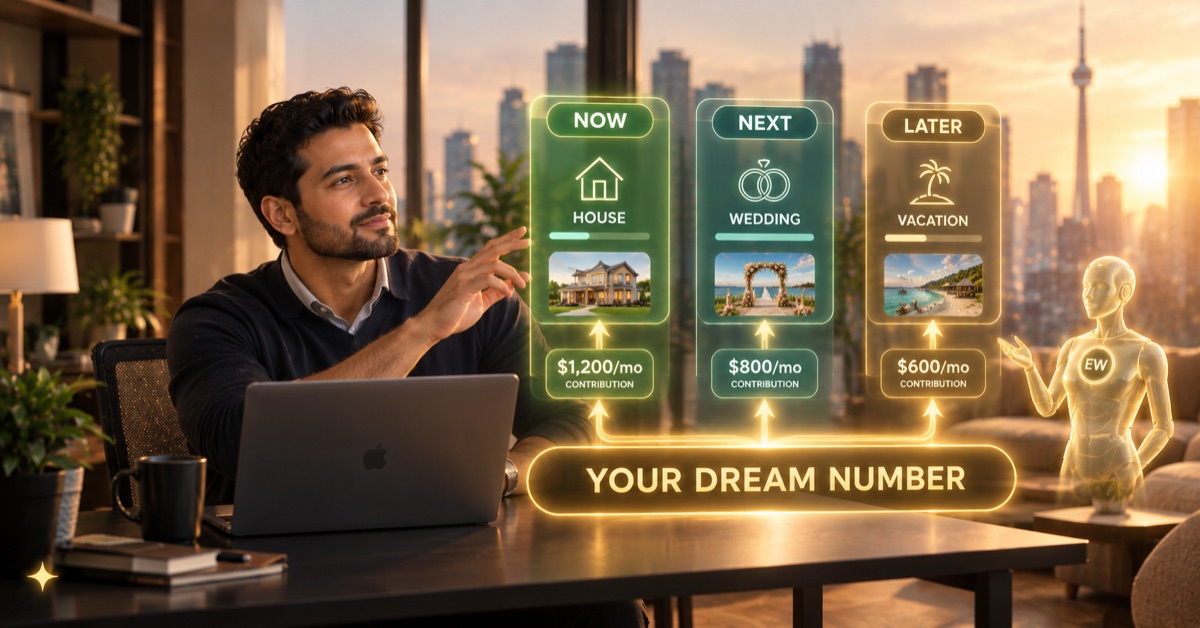
2. The Goal Stack Method (Now / Next / Later)
Now (under 2 years)
Emergency fund, car replacement, wedding, security deposit. Money lives in high-yield savings or short CDs. Capital preservation only.
Next (2-7 years)
House down payment, business launch, sabbatical, near-term tuition. Mix of cash and conservative bond/balanced funds.
Later (7+ years)
Retirement, kids' college if young, financial independence. Equity-heavy, tax-advantaged accounts, long-horizon discipline.
The point isn't how many goals you have. It's that every dollar you save knows which bucket it belongs to. When those goals start competing for the same paycheck, the order you fund them in becomes its own decision. That is a separate skill, and it has its own guide: how to prioritize financial goals without robbing one to pay another.
3. How to put a real price tag on each goal
- Today's cost. What would the goal cost in today's dollars?
- Inflation adjustment. Multiply by (1 + inflation rate)^years. Use 3% general, 5% healthcare, 5-7% college.
- Buffer. Add 10-20% for surprises. Always.
- Monthly contribution. Subtract existing balance, divide by months. For Later goals, factor in a 4-6% real expected return.
Worked example: down payment in 4 years
Today's target: $40,000. Inflation 3%: ~$45,000. 15% buffer: $52,000. Currently saved: $7,000. Monthly: ($52,000 minus $7,000) / 48 = ~$940/month.
If you're saving a down payment in Canada, which account holds that monthly contribution (FHSA, TFSA, or an RRSP Home Buyers' Plan withdrawal) changes the real number. See TFSA vs RRSP vs FHSA for a house down payment.
✓ What to do this week
4. Goal-based investing: matching money to timelines
| Horizon | Typical mix | Why |
|---|---|---|
| Under 2 years | 100% high-yield savings or CDs | No time to recover from a drawdown |
| 2-4 years | 70% cash/bonds, 30% equity | Some growth, limited downside |
| 4-7 years | 40% bonds, 60% equity | Balanced growth, manageable risk |
| 7+ years | 10-30% bonds, 70-90% equity | Time absorbs volatility; growth wins |
5. Execution layer: automate contributions and reviews
- Payday rule. The day after every paycheck, transfers fire automatically into the right goal account.
- Quarterly check-in (45 minutes). Confirm contributions are flowing. Note any goal that's drifted more than 10% off pace.
- Annual re-forecast (90 minutes). Re-price every goal with current inflation. Adjust contributions. Reconfirm priorities.
If this is your situation
Just starting out
Automate one goal first, usually the emergency fund. Once you trust the routine, add a second.
Building momentum
Run all goals through one tracker. A single dashboard makes trade-offs visible at a glance.
Optimizing
Layer in tax optimization: which goals belong in tax-deferred vs taxable, and how Roth/HSA/529 fit each.
6. Life happens: how to re-plan without losing momentum
- Job loss. Pause Later goals. Keep emergency fund and minimums on debt.
- New child. Add a 529. Increase emergency buffer to 6 months.
- Relocation. Re-price Now and Next goals at the new cost of living.
- Health event. Confirm HSA and insurance buffers. Move money out of long-horizon equity if needed within 24 months.
- Windfall. Don't deploy in week one. Park in cash. Apply your priority order.
✓ What to do this week
Frequently asked questions
What is the best way to plan financial goals?
Use a Goal Stack with three time horizons: Now, Next, and Later. Give every goal a target, a date, a monthly contribution, and a funding account.
How much should I save each month per goal?
Take the target, subtract what you have saved, and divide by the number of months, then add a 10 to 20 percent buffer. For long-horizon goals, factor in expected investment growth.
What is the Goal Stack method?
It sorts every goal into three time horizons: Now for under two years, Next for two to seven years, and Later for seven years or more. Each horizon gets a matching home for the money, from cash for Now goals to mostly equities for Later ones, so every dollar knows which bucket it belongs to. Deciding which goal to fund first when they compete is a separate step, covered in how to prioritize financial goals.
See your goals on one page
The EnvisionWorth calculator prices each of your financial goals on its own timeline and adds them into one monthly Dream Number, then shows where two goals compete for the same dollar and what a what-if change (delaying, resizing, or reordering a goal) does to the rest. It runs in your browser, and no account is needed to see your number.
Try the free calculator⚠️ Disclaimer
This content is for educational purposes only and does not constitute financial, investment, tax, or legal advice. EnvisionWorth provides technology and educational resources; we do not provide personalized financial advice. Past performance does not guarantee future results. All investment decisions should be made in consultation with qualified financial professionals.
Avish Shah
Founder, EnvisionWorth Financial Intelligence
EnvisionWorth helps you plan all your financial goals together, give every dollar a job toward a goal, and see what needs attention.
Continue Your Journey
Explore more insights to enhance your financial intelligence
Can You Afford a House and a Wedding in the Same Year?
Two goals that look affordable separately can be impossible together. The month-by-month numbers on funding a house deposit and a wedding at once, and the three ways out.
How to Prioritize Financial Goals Without Robbing One to Pay Another
Ranking goals is the easy part. This is what to do with the goals that lose: sequencing versus splitting, the real cost of delay by goal type, and when partial funding wins.
The Spreadsheet-and-Hope Method Is Costing You
A spreadsheet handles one goal well and several goals badly. The four things it structurally cannot model, how to tell yours has stopped working, and what to do about it.